

A new Ember analysis indicates that battery storage and demand-side flexibility could significantly reduce reliance on gas-fired plants for grid balancing in the European Union, as renewable penetration accelerates.

EU batteries and the future of grid flexibility in Europe
The rapid expansion of renewable energy across Europe is reshaping how electricity systems are managed. A new report by Ember suggests that battery storage systems and demand flexibility solutions are increasingly positioned to replace gas-fired power plants in providing short-term grid balancing services. The analysis draws on scenarios developed by European transmission system operators (TSOs) and highlights how storage technologies are becoming central to system stability.
Structural flexibility as renewables reshape the power system
At the core of the report is a clear structural shift: as variable renewable generation continues to expand, electricity networks require more flexible resources to manage fluctuations in supply and demand. According to Ember, this flexibility does not necessarily need to come from fossil fuel-based generation. Instead, batteries, electric vehicle charging and heat pumps are emerging as scalable alternatives capable of shifting electricity consumption and supply in time.
Rather than focusing on short-term energy price volatility or recent energy crises, the study concentrates on system design and investment trends. The key question is how effectively flexibility assets can shift demand and supply curves toward periods of high renewable availability.
EU batteries capacity expected to quadruple by 2030
The report estimates that installed battery capacity in the European Union could increase dramatically over the next five years, rising from around 43 GW at the end of 2025 to approximately 178 GW by 2030.
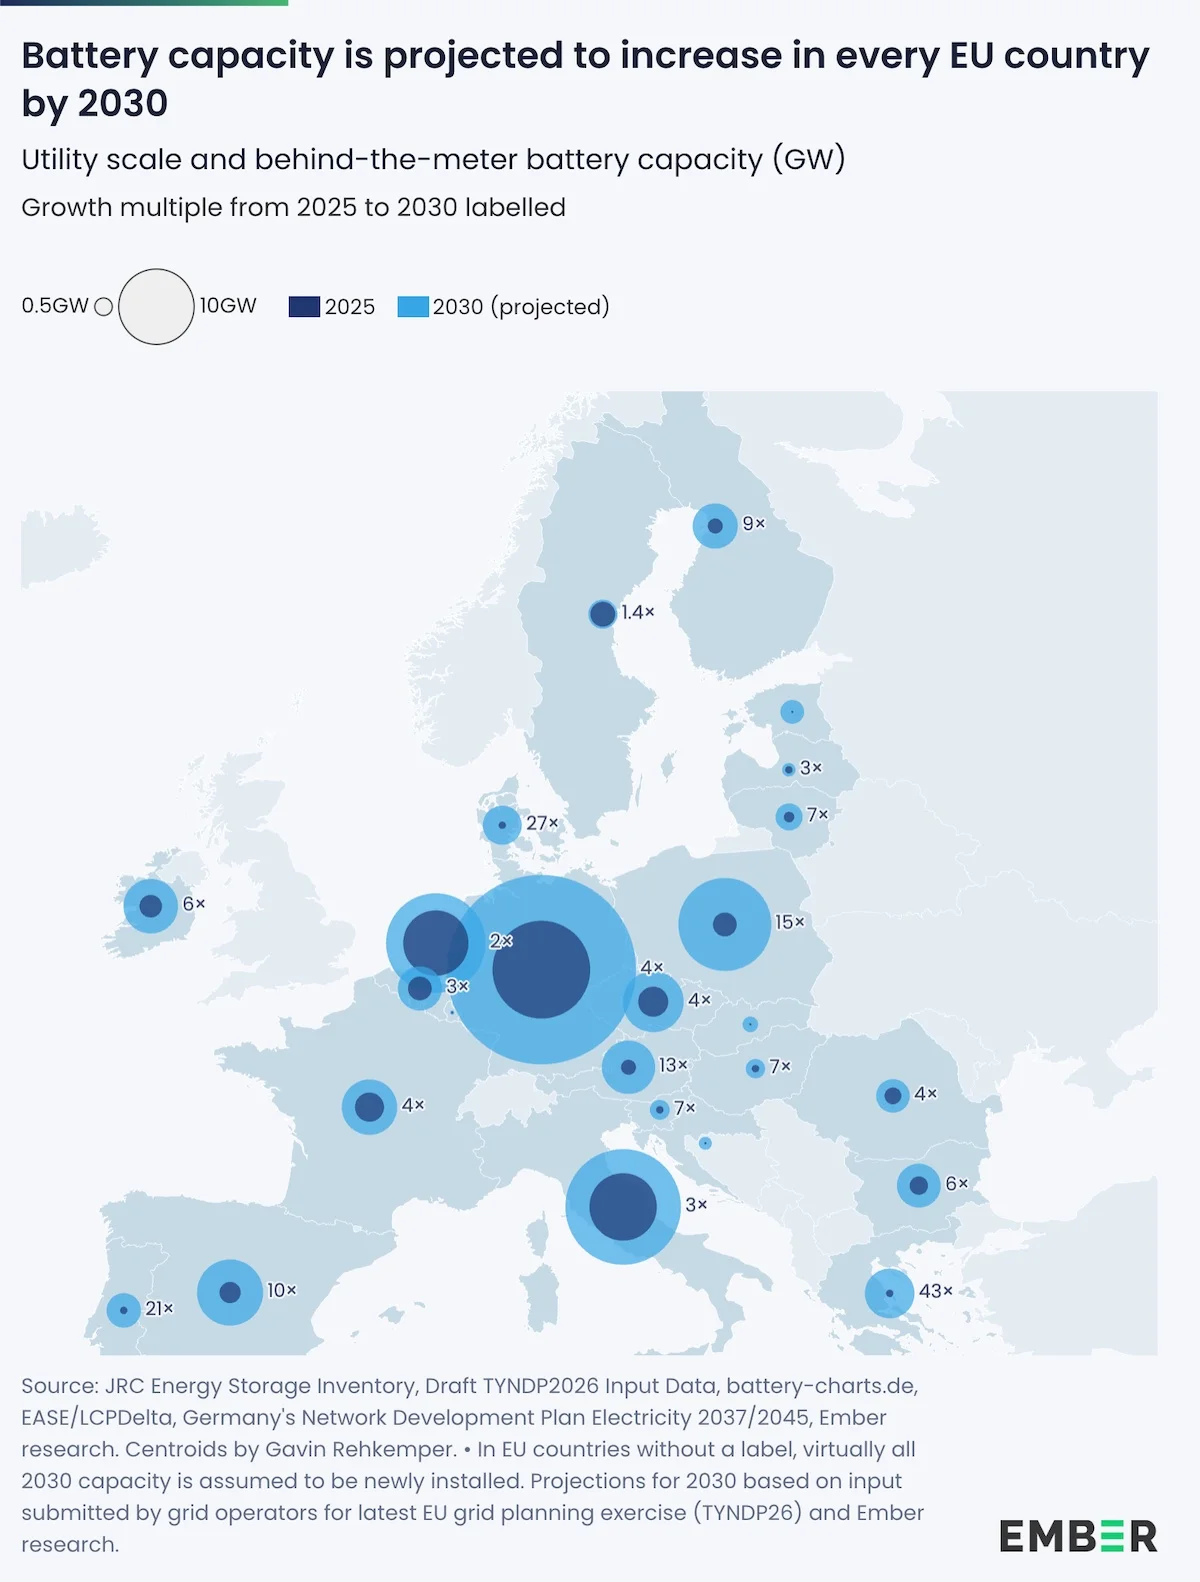
Large-scale battery energy storage systems (BESS), including grid-connected installations and systems paired with wind and solar plants, are expected to account for the majority of this growth.
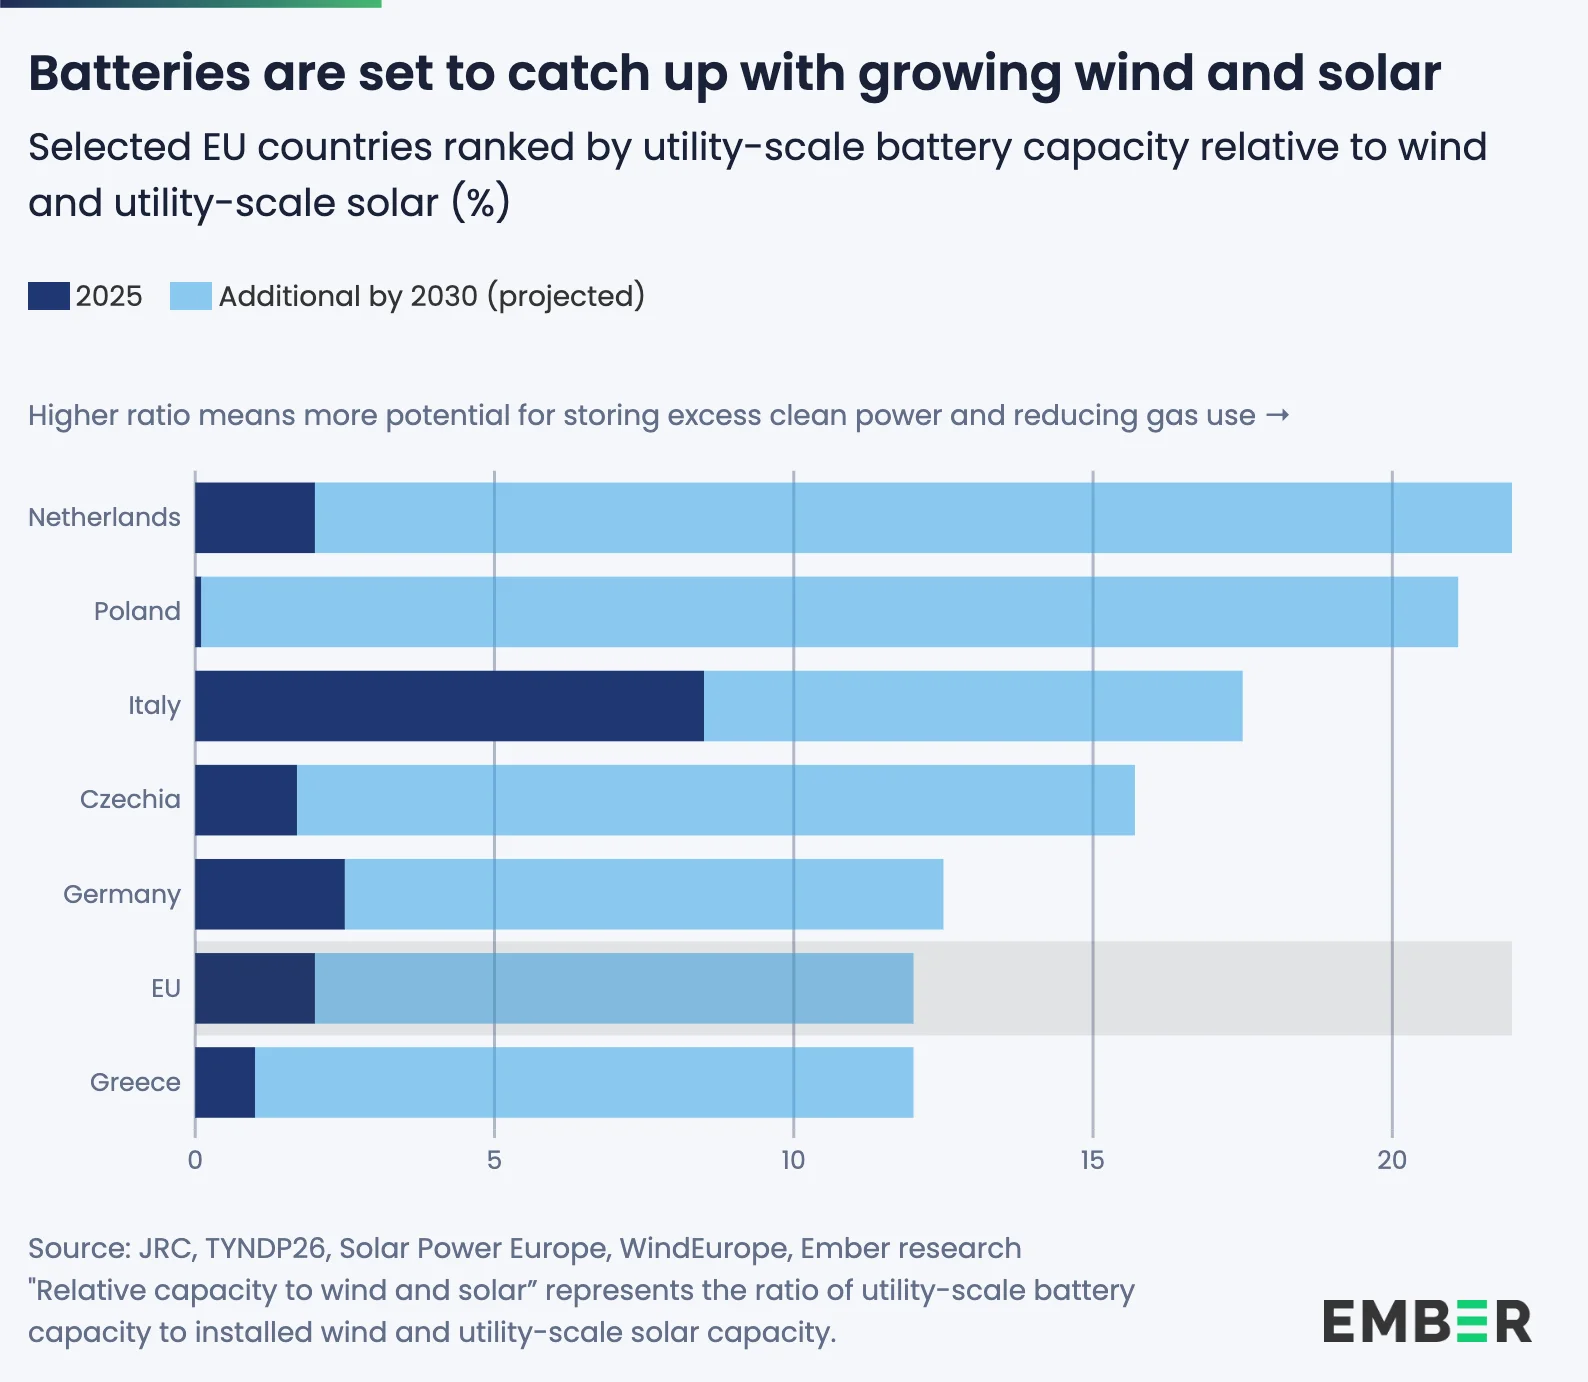
Together, these utility-scale segments are projected to reach about 107 GW by the end of the decade. Ember notes that for every 100 GW of wind and solar capacity, the EU currently has around 3 GW of large-scale storage, a ratio of 3%. By 2030, this could rise to 12%, reflecting a substantial increase in system flexibility.
Behind-the-meter batteries, installed in residential and commercial settings, are also expected to expand significantly, effectively doubling their installed capacity by 2030. Their growth will be driven largely by household and business investment decisions, although upfront costs remain a barrier in several markets.
EU batteries and cost competitiveness versus gas peaker plants
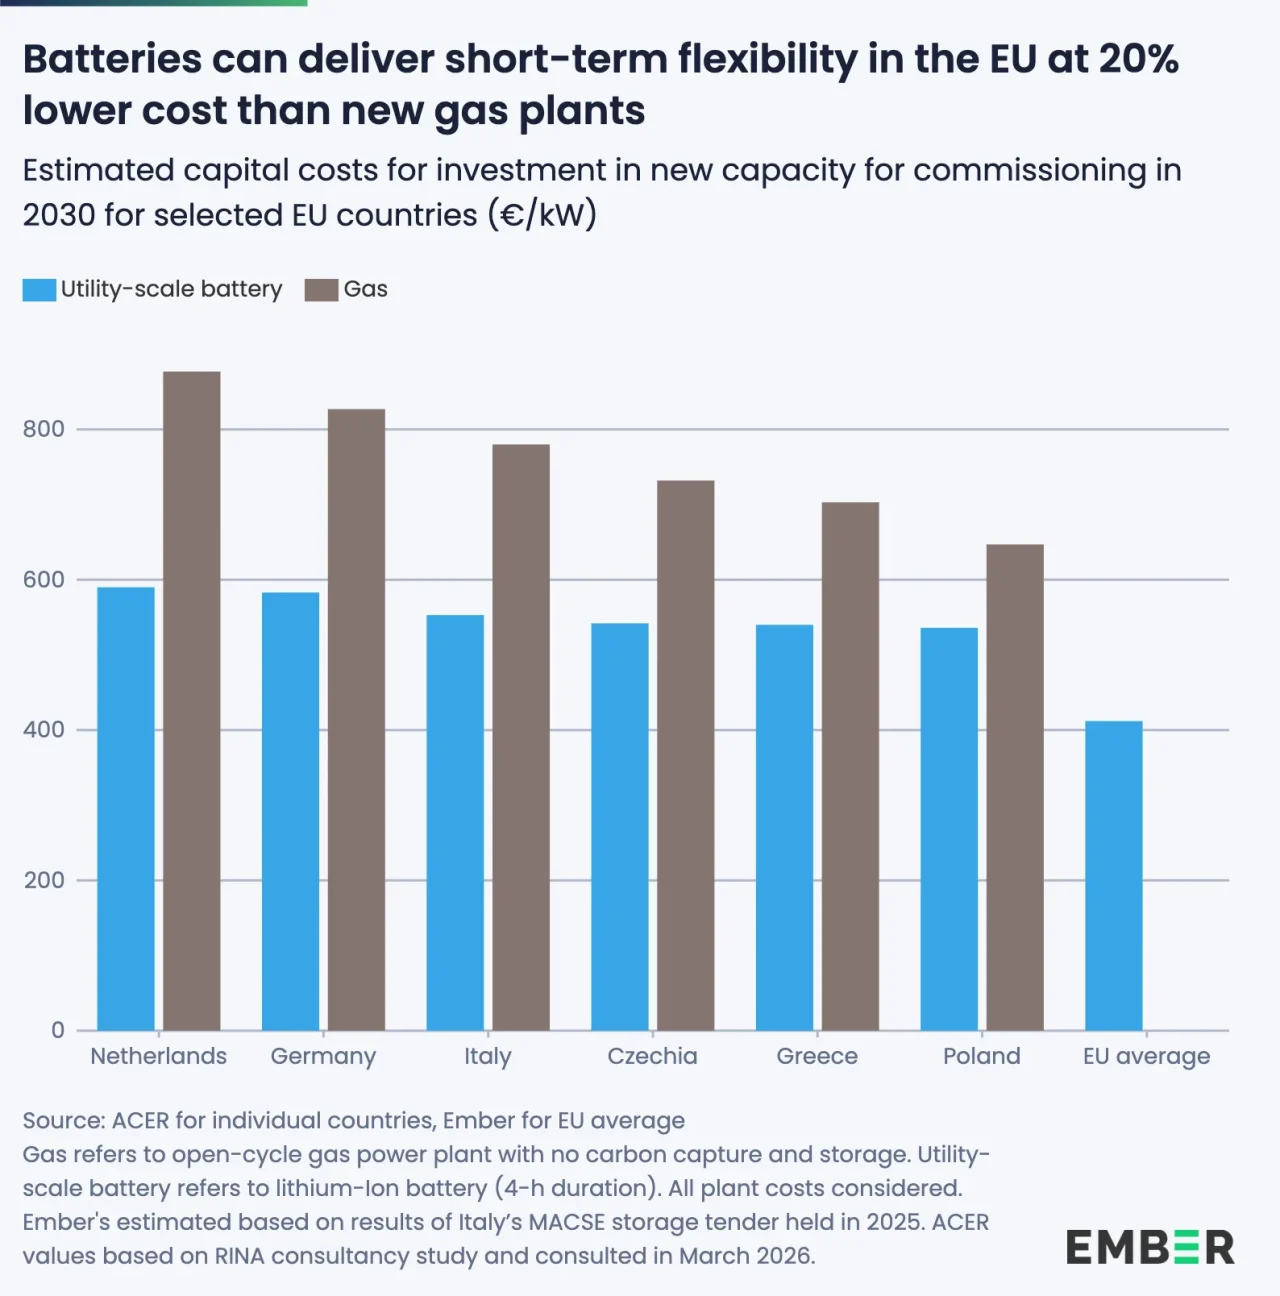
One of the most relevant findings of the report concerns cost competitiveness. Ember highlights that large-scale battery projects are increasingly able to compete with new gas peaker plants for short-duration flexibility services, while offering faster deployment times.
The improvement is linked both to economies of scale and to rising capital costs for new gas-fired infrastructure. As a result, utility-scale batteries are expected to provide short-term flexibility at costs up to 20% lower than new gas plants by the end of the decade.
In Italy, for example, capital costs for industrial-scale battery systems with four-hour duration are estimated at around €550/kW, compared with roughly €780/kW for new open-cycle gas turbines by 2030. This places Italy among the higher-cost markets for gas-based flexibility in Europe.
EU batteries replacing gas in grid balancing
The report also highlights a significant shift in operational capability. In 2025, all batteries in the EU combined could deliver only about 25% of the instantaneous output of all gas-fired plants. By 2030, this share is expected to exceed 80%, indicating a structural change in how balancing services are provided.
If installed capacity reaches 178 GW as projected, battery storage could enable the shifting of around 10% of daily solar and wind generation from midday peaks to evening demand periods, compared with about 5% today. Behind-the-meter systems alone could shift up to 17% of rooftop solar generation by 2030.
As Ember analyst Dr Beatrice Petrovich notes, clean flexibility is no longer a theoretical option but an emerging reality. The challenge ahead, she argues, lies not in technological readiness, but in implementation, regulatory frameworks and incentives capable of scaling flexibility fast enough to avoid continued reliance on fossil backup generation.


